₹99 Is Enough to Start: Gig Workers Are Getting NPS Pensions
PFRDA plans to open NPS accounts for gig workers on the e-shram database, with contributions as low as ₹99. Here is how the e-shramik model works and what riders and side hustlers should know.
Over 2 lakh delivery partners on Zomato have already opened pension accounts. Together, their small, regular deposits have crossed ₹1 crore.
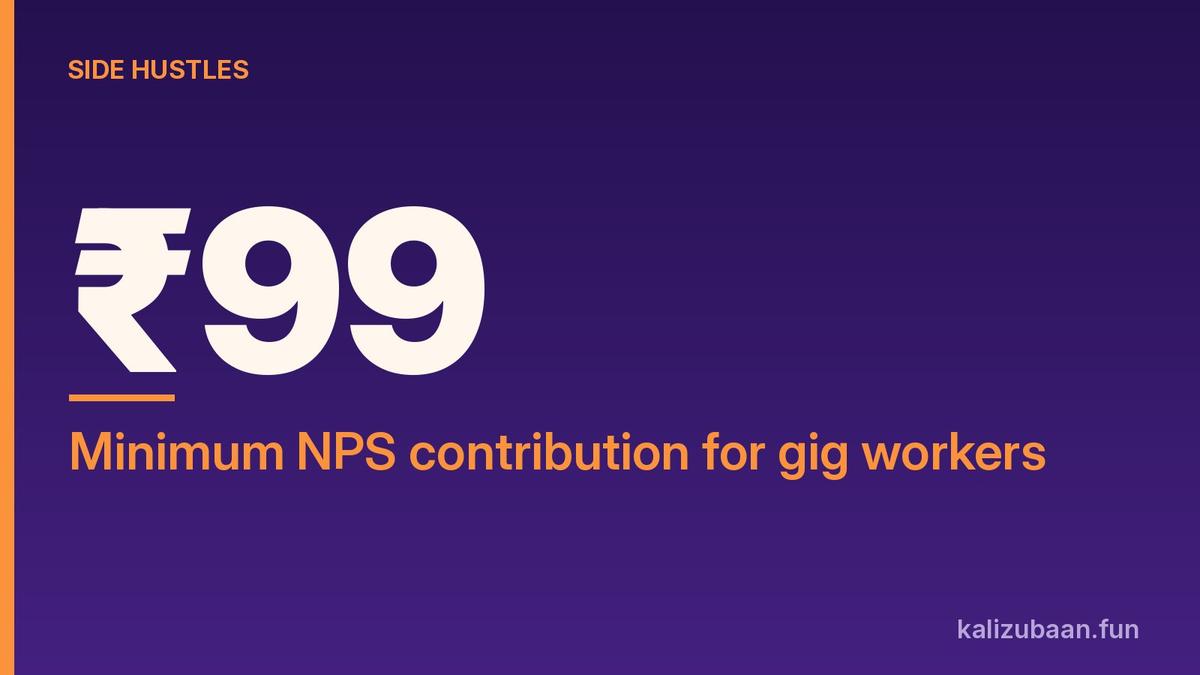
Now the pension regulator wants to do the same for lakhs more gig and platform workers. And the entry ticket is tiny: contributions can be as low as ₹99, with no fixed monthly amount.
Quick answer
- PFRDA, the pension regulator, is tying up with the e-shram database to open National Pension System (NPS) accounts for gig and platform workers, with their consent.
- Accounts will open through NPS Tatkal, a digital option that works through UPI-linked payment platforms without paperwork.
- Under the e-shramik model, workers and platforms can make flexible micro-contributions as low as ₹99, without rigid monthly mandates.
- The account is tied to a Permanent Retirement Account Number (PRAN), so it stays with you even if you switch apps or stop gig work.
What PFRDA is planning for gig workers
The Times of India reported that PFRDA is working to open NPS accounts for gig and platform workers who are registered on the e-shram database.
"Under the social security code, govt has to provide social security benefits to gig and platform workers," PFRDA chairman S Raman told TOI. "We are tying up with the e-shram database now, will get a consent from the gig workers and open NPS accounts for them."
These accounts will use NPS Tatkal, which lets subscribers open an account digitally and instantly through UPI-linked payment platforms. No paperwork is needed.
By default, the new accounts will follow the NPS Sanchay investment pattern. TOI describes this as a pre-defined, conservative-to-moderate mix, similar to government sector NPS schemes. Subscribers can change their allocation later if they want.
How the e-shramik model works
The NPS e-shramik model was launched in October 2025. It was built for people whose earnings are irregular, which is exactly what gig and side-hustle income looks like.
Here is what makes it different from a regular pension plan:
- Micro-contributions. Deposits can be as small as ₹99.
- No monthly mandate. You are not locked into paying a fixed amount every month.
- Two payers. Both the worker and the platform can contribute.
- Portability. The PRAN stays with you, irrespective of which platform you work with.
TOI notes that this flexibility matters because platforms have not been very forthcoming about how much they will contribute towards workers' social security. A model where anyone can chip in, in any amount, sidesteps that fight.
For workers without regular earnings, it means starting to save for retirement now instead of deferring it.
What the Zomato numbers show so far
Zomato was an early adopter. In a press release in August, it said the NPS corpus built by delivery partners on its platform had crossed ₹1 crore, with enrolments passing 2 lakh PRANs.
The model was introduced with HDFC Pension, with KFintech as the central recordkeeping agency. Onboarding uses the delivery partner's existing KYC or eKYC, with consent.
For context, Zomato says it supports an average of 6,38,000 monthly active delivery partners. So while 2 lakh enrolments is a real start, most of its fleet has not signed up yet.
PFRDA's chief general manager Sumit Kumar said the milestone shows that "even small, regular contributions can collectively create a meaningful foundation for the future."
Mint's interview with Raman adds that gig workers are often financially aware and actively ask for NPS contributions. The bigger problem has been access. Platforms such as Uber, Swiggy, Zomato and Urban Company already deduct a specified amount from payouts and send it directly to NPS.
What happens if something goes wrong
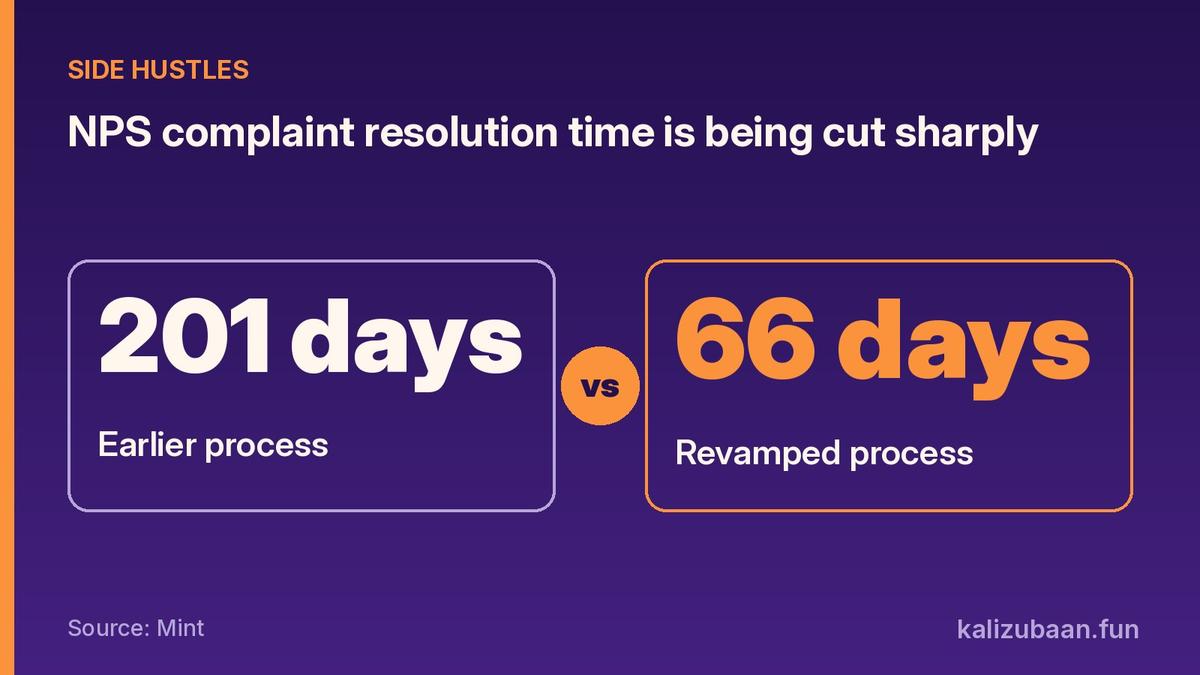
A fair worry with any government-linked account is getting stuck when a deposit doesn't show up. Raman told Mint that PFRDA has revamped its grievance system.
Source: Mint
The process is being reduced from around 201 days to 66 days, including the ombudsman stage. The first level is handled by the intermediary, and the second level goes directly to PFRDA.
Real-time information through Pension Sahayak should also stop simple questions, like a missing contribution or your balance, from turning into formal complaints.
How to think about this if you ride, deliver or freelance
If you do gig work on the side of a job, you may already have EPF or NPS through your employer. This is mainly useful for people whose main income is gig or platform work, or who freelance with no employer benefits at all.
A few practical points:
- Check your e-shram registration. PFRDA's plan starts from the e-shram database, so being registered is the first step.
- Start with what you can spare. The ₹99 floor means a slow week does not break the habit.
- Look at the default mix. NPS Sanchay is conservative-to-moderate. If you are young and want more equity, TOI says you can change the allocation later.
- Keep your PRAN safe. It is your account number for life, across every app you work with.
Wikipedia notes that NPS is a defined-contribution system regulated by PFRDA, open to Indian citizens aged 18 to 70. That means your final pension depends on what goes in and how it grows, not on a fixed promise.
Scams to watch for
Because accounts open through UPI-linked platforms, expect fake "NPS registration" links on WhatsApp. Only use your platform's app, official NPS channels or a recognised point of presence.
Nobody legitimate needs your UPI PIN to open a PRAN. If someone asks for a fee to "activate" a gig worker pension, walk away.
FAQs
Who can get an NPS account under this plan? PFRDA plans to open accounts for gig and platform workers in the e-shram database, after getting their consent.
What is the minimum contribution? Under the e-shramik model, contributions can be as low as ₹99, with no rigid monthly mandate.
What happens if I switch from one delivery app to another? Your account is linked to a PRAN, so you can access it irrespective of your platform or employment.
Where is the money invested by default? In the NPS Sanchay pattern, a conservative-to-moderate mix. You can change it later.
Results vary; nothing here is a promise of income or returns. This is information only, not investment or tax advice; check with a qualified adviser or CA for your situation.
Do you do gig work on the side? Would you put ₹99 a week into a pension, or does that money need to stay in your pocket right now?
Sources
Tagged Topics
Keep reading
Thanks for reading Kali Zubaan
Explore more articles in Side Hustles or return to the main publication feed.


